Learn All About Personal Liability In Homeowners Insurance
Key Takeaways
- Blocking Heavy Lawsuits: Basic papers pay hospital invoices, missing paychecks, and brutal courtroom lawyers whenever random strangers get completely wrecked visiting a house. This exact contract also handles neighborhood destruction sparked directly by rowdy kids, bad dogs, or clumsy owners.
- Zero Illegal Coverage: Giant corporations absolutely reject payouts involving street crimes, intentional fistfights, or hidden basement hustles. Folks running side gigs absolutely must buy heavy corporate papers preventing total financial wipeouts.
- Setting Massive Limits: Smart operators demand locking down exactly three hundred grand minimum. Anyone holding incredibly dangerous backyard toys, like deep concrete pools or rusty trampolines, absolutely needs massive umbrellas completely preventing bankruptcy.
A homeowners insurance policy isn’t just about protecting your home from damage and providing coverage for the things you own. It also provides important liability protection if someone is injured while on your property or if you are sued for damages related to your property or activities. Personal liability coverage is an important part of any homeowners policy, yet many people don't understand what it covers or how it works. In this article, we'll take a closer look at personal liability coverage and why it's important.
Exploring Personal Liability Coverage
Personal liability coverage is part of a standard homeowners insurance policy and provides protection if you are found legally responsible for an accident or injury that occurs on your property or due to your actions. This coverage pays for the other person's medical bills, lost wages, and other associated costs up to the limits of your policy. It also pays for the cost of defending you in court if you are sued and includes coverage for damages you may be found liable for.
Personal liability coverage is designed to provide protection in the event you inadvertently cause an injury to someone else or damage their property. For example, if your child throws a ball through a neighbor's window, your personal liability coverage will pay for the damages. Similarly, if someone slips and falls on your property and injures themselves, your policy will provide coverage for their medical expenses and any other damages they may be entitled to.
What is Not Covered by Personal Liability Coverage?
Personal liability coverage does not provide protection for intentional acts or illegal activities. This means that if you intentionally cause damage to someone else's property or harm them in any way, your insurance policy will not provide coverage. Similarly, if you are charged with a crime or sued for damages related to an illegal activity, your policy will not provide coverage.
In addition, personal liability coverage does not provide protection for business-related activities. If you are sued or held liable for damages related to your business activities, you will need to purchase a separate business liability policy.
Amount of Personal Liability Coverage
The amount of personal liability coverage you should have depends on your specific needs and circumstances. Generally, it is recommended that you purchase coverage for at least $300,000. This should provide enough coverage for most common liability claims. However, if you own high-value items or are involved in risky activities, you may need to purchase additional coverage.
Examples of Personal Liability Claims
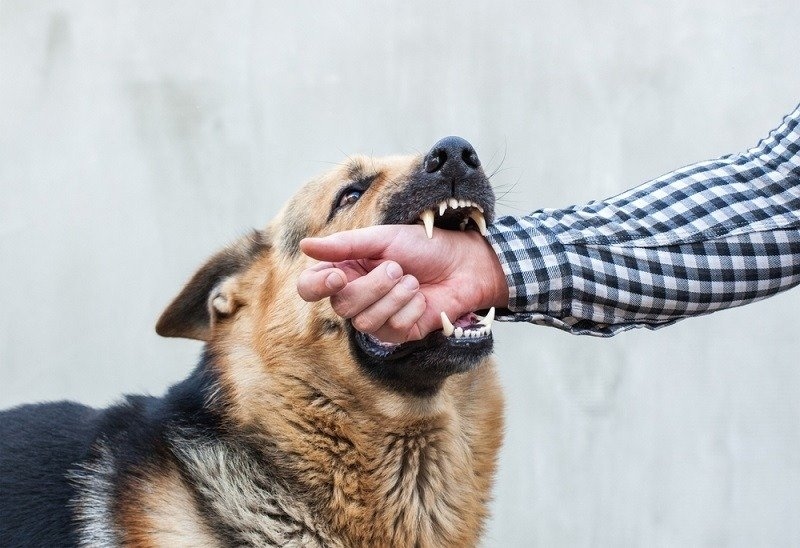
Personal liability claims can arise from a variety of situations. Some of the most common examples include:
- Injury caused by an object on your property, such as a broken tree limb
- Injury caused by a pet you own
- Injury caused by a recreational activity on your property, such as a swimming pool or trampoline
- Damage caused by your child to a neighbor's property
- Libel or slander
- Damage to someone else's property due to your negligence
Benefits of Personal Liability Coverage
There are several benefits to having personal liability coverage. First, it provides financial protection in the event you are sued or held liable for damages. This can help prevent you from having to pay out of pocket for costly legal fees and damages.
Personal liability coverage provides peace of mind knowing you are protected if something unexpected happens. This can help you feel secure in your home and in your activities knowing that you have the right coverage in place.
Having personal liability coverage can help you maintain a positive relationship with your neighbors. If someone is injured on your property or their property is damaged due to an accident, your insurance policy will provide coverage for the damages. This can help prevent any bad feelings or animosity that could arise from an incident.
Drawbacks of Personal Liability Coverage
Personal liability coverage does have some drawbacks. First, it can be expensive to purchase additional coverage if you need it. If you have high-value items or are involved in risky activities, you may need to purchase additional coverage to ensure you are adequately protected.
Personal liability coverage does not provide protection for intentional acts or illegal activities. If you cause intentional harm to another person or damage to their property, your policy will not provide coverage. Additionally, if you are sued or held liable for damages related to an illegal activity, your policy will not provide coverage.
It does not provide protection for business-related activities. If you are sued or held liable for damages related to your business activities, you will need to purchase a separate business liability policy.
What Should I do if I Have a Personal Liability Claim?
If you have a personal liability claim, the first thing you should do is contact your insurance company. They will be able to explain the claims process and provide any assistance you may need. It is important to keep detailed records of all conversations and correspondence with your insurance company to ensure your claim is handled properly.
You should also contact an experienced attorney if you are sued or held liable for damages related to your property or activities. An attorney can help you navigate the legal process and protect your rights.
Conclusion
An essential component of every homeowner's insurance policy is personal liability coverage. If you are held legally accountable for an accident or harm that takes place on your property or as a result of your activities, it offers financial protection. Despite its shortcomings, it might provide you a sense of security knowing you are covered in the event of an emergency.
In order to obtain the appropriate level of coverage for your requirements, it is crucial to understand what personal liability coverage includes and excludes. It is crucial to get in touch with your insurance provider or a qualified lawyer if you have any queries concerning personal liability coverage or want assistance with a claim.
Frequently Asked Questions
What exact damages do basic liability papers handle?
Contracts instantly pay heavy hospital invoices, missing paychecks, and brutal courtroom lawyers whenever a homeowner completely destroys another person physically on the actual property dirt.
What specific accidents actually trigger heavy lawsuits?
Massive triggers include nasty dog bites, brutal icy falls, crushed wooden fences, and random baseballs shattering glass. Upgraded contracts also block nasty public defamation rumors.
Do basic residential contracts actually cover messy business accidents?
Never. Standard residential papers strictly ban all basement hustles. Only founders absolutely must buy heavy corporate papers, preventing total financial destruction fast.
What exact liability amount must a property owner grab?
Smart operators demand locking down exactly three hundred grand minimum. Anyone holding deep swimming pools or vicious guard dogs absolutely buys massive umbrellas, preventing total bankruptcy.
What exact steps must happen following a brutal injury?
Homeowners absolutely must call the corporate hotline instantly and hoard all bloody photographs. Hiring a nasty courtroom lawyer becomes entirely mandatory whenever injured strangers demand cash.
This content was created by AI
©2026 InsuranceAndLeisure.com, All Rights Reserved